
October Observations
Mixed Market with Tech Under Pressure
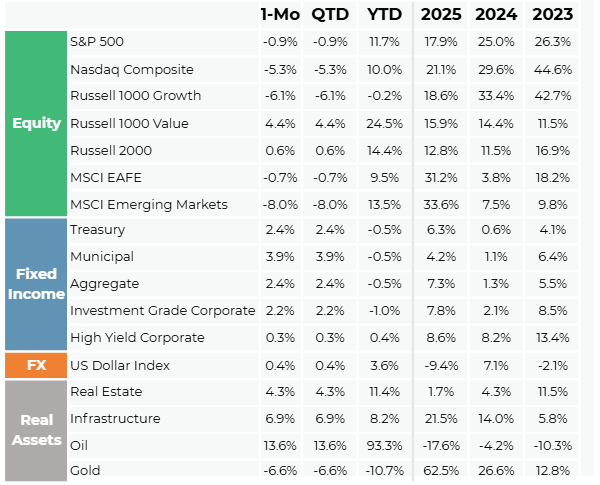
Markets in October continued to evaluate the direction of monetary policy, economic growth, corporate earnings, and inflation. U.S. equities experienced a modest pullback. The S&P 500 declined approximately 0.9% in October while the Dow Jones Industrial Average gained 1.8%. The Nasdaq Composite was weaker, falling 5.3% as technology stocks faced increased pressure over concerns surrounding capital expenditures for AI infrastructure and financing needs. Energy, consumer staples, healthcare, and utilities were among the stronger-performing sectors and value stocks outperformed growth stocks. On the international equity side developed international markets were relatively resilient for the month of October, however, emerging markets experienced significant weakness. Emerging markets declined approximately 8% mainly driven by concerns surrounding AI valuations and competition. Developed markets had a more modest of only 0.7% decline. The US 10-year Treasury yield declined 31 bps over the month, ending at 4.93%. The move reflected a combination of safe haven demand amid equity volatility and credit market stress. Crude oil surged 13.6% to $120 per barrel with the move driven by elevated geopolitical risk, including Iranian attacks on vessels in the Strait of Hormuz.
FOMC Holds Steady
The late month FOMC meeting produced a 10-2 vote to hold rates steady at 3.75%-4.00%, though the 2 dissenters pushed for a rate hike. The committee opted for a patient approach, stating that “the accumulation of more information will help the Committee determine the policy stance appropriate to ensure a timely return of inflation to….2 percent”. Markets have shifted their expectations for a quarter percent rate hike at the next meeting December 9.
Anthropic IPO Announcement
On October 26 AI giant Anthropic filed registration with the SEC for a proposed IPO of its Class A common stock on the Nasdaq. This was a landmark moment as it was the first frontier AI model company to pursue a public listing. Wall Street’s initial read on the filing was broadly positive, however, a combination of market conditions and timing pressure appear to be creating friction for its trading debut. The IPO has not yet priced or traded and remains a private company.
Asset Manager Commentary
US Mid Cap Value Manager
Current valuations of the rolling ten-year growth in S&P 500 earnings per share describes corporations as “over-earning.” Readings are above the level seen in the dot-com era and are approaching the post-World War II record highs. This does not mean the boom is certain to peak soon, but that exceptional margins could normalize. A sizable group of “orphaned” companies that are neither AI disruption targets nor AI beneficiaries or leaders, are priced as if current conditions will last indefinitely.
Emerging Markets Manager
The AI hardware cycle remains in its early-stage, with only about 2% of enterprises past the pilot phase, and demand for memory chips extends beyond 2030. Additionally, the market is pricing in earnings declines for several technology companies beginning around 2028, which does not reflect the supply and demand dynamics. The use of a barbell of structural growth and commodity companies can provide diversification when technology holdings have pulled back.
Chart of the Month
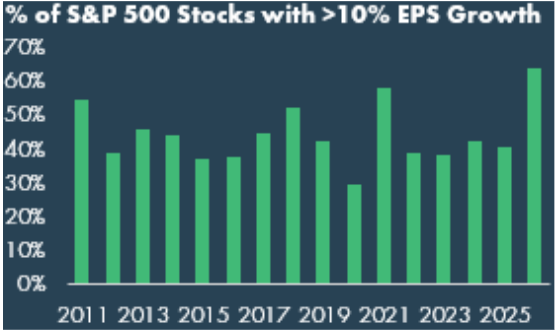
Despite the perceived negative implications from recent drawdowns in equities, earnings growth for roughly 64% of stocks in the S&P 500 are at 10% or more year-over-year.
Disclosures
© 2026 Advisory services offered by Moneta Group Investment Advisors, LLC, (“MGIA”) an investment adviser registered with the Securities and Exchange Commission (“SEC”). MGIA is a wholly owned subsidiary of Moneta Group, LLC. Registration as an investment adviser does not imply a certain level of skill or training. The information contained herein is for informational purposes only, is not intended to be comprehensive or exclusive, and is based on materials deemed reliable, but the accuracy of which has not been verified.
Trademarks and copyrights of materials referenced herein are the property of their respective owners. Index returns reflect total return, assuming reinvestment of dividends and interest. The returns do not reflect the effect of taxes and/or fees that an investor would incur. Examples contained herein are for illustrative purposes only based on generic assumptions. Given the dynamic nature of the subject matter and the environment in which this communication was written, the information contained herein is subject to change. This is not an offer to sell or buy securities, nor does it represent any specific recommendation. You should consult with an appropriately credentialed professional before making any financial, investment, tax or legal decision. An index is an unmanaged portfolio of specified securities and does not reflect any initial or ongoing expenses nor can it be invested in directly. Past performance is not indicative of future returns. All investments are subject to a risk of loss. Diversification and strategic asset allocation do not assure profit or protect against loss in declining markets. These materials do not take into consideration your personal circumstances, financial or otherwise.
Sources
Morningstar Direct, Baird Strategas, Bloomberg as of 10/31/2026
Manager comments come from discussions with various asset managers and are broad commentary on sectors and not be considered recommendations by any asset manager. These comments do not necessarily reflect strategy allocations or the view or opinion of MGIA or Moneta Group .
Definitions
The S&P 500 Index is a free-float capitalization-weighted index of the prices of approximately 500 large-cap common stocks actively traded in the United States.
The NASDAQ Composite Index is a market capitalization weighted index with more than 3000 common equities listed on the NASDAQ Stock Market.
The NASDAQ 100 Index is a modified capitalization-weighted index of the 100 largest and most active non-financial domestic and international issues listed on the NASDAQ..
The Russell 1000® Index is an index of 1000 issues representative of the U.S. large capitalization securities market.
The Russell 1000® Growth Index measures the performance of the large-cap growth segment of the U.S. equity universe. It includes those Russell 1000 companies with higher price-to-book ratios and higher forecasted growth values.
The Russell 1000® Value Index measures the performance of those Russell 1000 Index securities with lower price-to-book ratios and lower forecasted growth values, representative of U.S. Securities exhibiting value characteristics.
The Russell 2000® Index is an index of 2000 issues representative of the U.S. small capitalization securities market.
The MSCI EAFE Index is a free float-adjusted market capitalization index designed to measure the equity market performance of developed markets, excluding the U.S. and Canada.
The MSCI Emerging Markets Index is a float-adjusted market capitalization index that consists of indices in 21 emerging economies.
Bloomberg U.S. Treasury Bond Index includes public obligations of the US Treasury, i.e. US government bonds. Certain Treasury bills are excluded by a maturity constraint. In addition, certain special issues, such as state and local government series bonds (SLGs), as well as U.S. Treasury TIPS, are excluded.
The Bloomberg U.S. Municipal Index covers the USD-denominated long-term tax exempt bond market. It includes general obligation and revenue bonds, which both can be pre-refunded years later and get reclassified as such.
The Bloomberg U.S. Aggregate Bond Index is an index, with income reinvested, generally representative of intermediate-term government bonds, investment grade corporate debt securities and mortgage-backed securities.
The Bloomberg US Corporate Bond Index measures the investment grade, fixed-rate, taxable corporate bond market. It includes USD-denominated securities publicly issued by US and non-US industrial, utility and financial issuers.
The Bloomberg US Corporate High Yield Bond Index measures the USD-denominated, high yield, fixed-rate corporate bond market. Securities are classified as high yield if the middle rating of Moody’s, Fitch and S&P is Ba1/BB+/BB+ or below. Bonds from issuers with an emerging markets country of risk, based on the indices’ EM country definition, are excluded.
The US Dollar Index measures the US dollar against six global currencies: the euro, Swiss franc, Japanese yen, Canadian dollar, British pound, and Swedish krona.
The FTSE Nareit All Equity REITs Index is a free-float adjusted, market capitalization-weighted index of U.S. equity REITs. Constituents of the index include all tax-qualified REITs with more than 50 percent of total assets in qualifying real estate assets other than mortgages secured by real property.
The S&P Global Listed Infrastructure Index measures the performance of global companies that are engaged in infrastructure and related operations. It provides liquid and tradable exposure to 75 companies from around the world that represent the listed infrastructure universe. To create diversified exposure, the index includes three distinct infrastructure clusters: utilities, transportation and energy.
Brent Crude is the most traded of all of the oil benchmarks, and is defined as crude mostly drilled from the North Sea oilfields: Brent, Forties, Oseberg and Ekofisk (collectively known as BFOE).
The Dow Jones Commodity Index Gold is designed to track the gold market through futures contracts.
The ICE BofA Option-Adjusted Spreads (OASs) are the calculated spreads between a computed OAS index of all bonds in a given rating category and a spot Treasury curve. An OAS index is constructed using each constituent bond’s OAS, weighted by market capitalization. The Corporate Master OAS uses an index of bonds that are considered investment grade (those rated BBB or better). When the last calendar day of the month takes place on the weekend, weekend observations will occur as a result of month ending accrued interest adjustments.
The ICE BofA Option-Adjusted Spreads (OASs) are the calculated spreads between a computed OAS index of all bonds in a given rating category and a spot Treasury curve. An OAS index is constructed using each constituent bond’s OAS, weighted by market capitalization. The ICE BofA High Yield Master II OAS uses an index of bonds that are below investment grade (those rated BB or below).
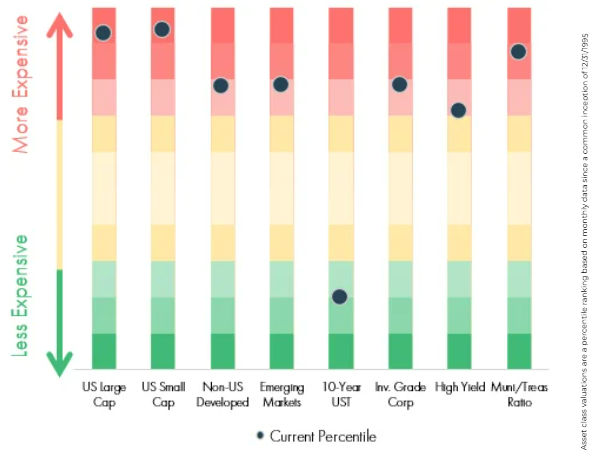
Asset class valuations are a percentile ranking based on monthly data going back to common inception of 12/31/1995. The US Large Cap percentile is the average percentile ranking of the trailing P/E, P/B, P/S, and P/C ratio of the S&P 500 Index. The US Small Cap percentile is the average percentile ranking of the trailing P/E, P/B, P/S, and P/C ratio of the Russell 2000 Index. The International Developed percentile is the average percentile ranking of the trailing P/E, P/B, P/S, and P/C ratio of the MSCI EAFE Index. The Emerging Market percentile is the average percentile ranking of the trailing P/E, P/B, P/S, and P/C ratio of the MSCI Emerging Markets Index. The 10-Year US Treasury percentile is the percentile ranking of the 10-Year US Treasury yield. The Investment Grade percentile is the percentile ranking of the ICE BofA US Corporate option adjusted spread. The High Yield Corporate percentile is the percentile ranking of the ICE BofA US High Yield corporate option adjusted spread. The Municipal/Treasury percentile is the percentile ranking of the Bloomberg Municipal Index yield divided by the 10-Year US Treasury Yield.
Related Topics to Explore

Tax Policy Outlook with Tax Foundation’s Garrett Watson
October 28, 2026
The tax landscape is ever evolving, complicated and wrought with uncertainty as the political winds shift form election-…

Third Quarter 2026 Investment Update
October 20, 2026
Executive Summary The third quarter of 2026 reinforced a market environment in which economic resilience and corporate e…


Monthly Recap – August 2026
September 10, 2026
August Observations Markets Recover from a Summer Lull After two weaker months, US equity markets were in a risk-on mood…